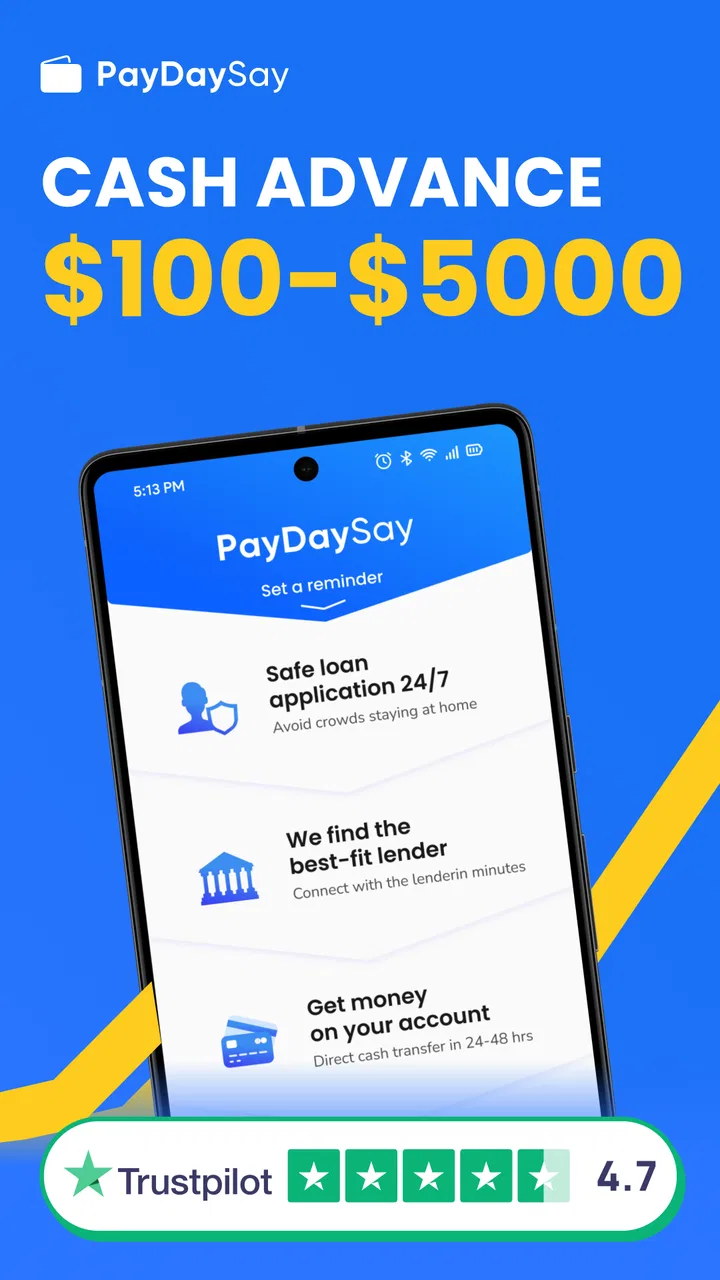
Cash Advance Now - PayDaySay
- 4.6
- Rating
- 100.00K
- Installs
- Free
- Price
 Analysis by App-foxy
When an unexpected bill lands before payday, the appeal of Cash Advance Now - PayDaySay is easy to understand: it is a finance app built around requesting a small cash advance rather than arranging a traditional loan. I found its purpose refreshingly narrow. It is not trying to be a full banking replacement, a budgeting dashboard, or an investment platform. The focus is getting through a short-term cash gap, and that makes the app easier to judge honestly.
My first impression was that the experience is designed for urgency. The app comes from PayDaySay, is free to install, and is rated for Everyone. It has reached over 100 thousand installs, with an average rating of 4.6 from around 16 thousand ratings. Those figures suggest that many people find the basic idea useful, although popularity should never replace checking the actual terms of any borrowing service before accepting money.
I would describe it as a tool for a very specific moment: you need a modest amount, you expect income soon, and you want to explore an advance without visiting a branch. That narrow use case is also its main warning. A fast request is not the same as affordable borrowing, and an app that helps today may create a harder repayment problem later.
You May Also Like

 Blood Strike: 2.5 Anniversary
Blood Strike’s Loadouts Turn Every Drop Into a Tactical Gamble
A close look at Blood Strike’s custom loadouts: how fast access to signature weapons reshapes its battle royale rhythm, rewards preparation, and narrows the gap between fights.

 Pandora - Music & Podcasts
Pandora’s Music Is Easy to Start, but Harder to Recover
Pandora’s strength is its low-effort path from a seed to a station. Its weak spot is how much confidence it asks you to place in connection, setup, and quiet recovery.

 8 Ball Pool
 Is Built on Rivalries, Rematches, and Routine
A close look at the rivalries, rematches, shared routines, and unanswered safety questions that turn a quick pool match into a persistent mobile community.

 Samsung Music
’s Quiet Strength Is Playing What You Already Own
Its reach comes less from spectacle than from dependable access to a personal library. That simplicity is both the app’s strongest retention engine and its ceiling.

 AccuWeather: Weather Radar
AccuWeather Review: A Quick, Clear Forecast for Everyday Decisions
For everyday plans, the best forecast is the one you can understand quickly. AccuWeather makes rain timing, radar, and local conditions easy to act on, with a few trade-offs.

 Hill Climb Racing
Why Hill Climb Racing Still Turns Crashes Into One More Run
A tiny car, a bumpy hill and one more upgrade: Hill Climb Racing keeps resurfacing because its simple chaos makes every near-miss feel personal.
More From Our News Desk



How the app feels when speed matters
I find that speed is most useful when it helps me make a deliberate decision, not when it nudges me to accept before I have read the repayment terms. In this section, I focus on how to keep a time-sensitive request manageable: decide the amount first, then pause at each confirmation screen long enough to understand what comes next. That same careful routine also matters when I return to the app repeatedly.
What “instant” means in practical use
The strongest part of the concept is the reduction in friction. Instead of beginning with a long search through unrelated lenders, I can approach the app with one question: can it help me cover this immediate shortfall? That directness matters when a payment is due soon or an everyday expense cannot reasonably wait.
Still, I would not treat the word “instant” as a promise that every request ends with money immediately available. A cash advance normally depends on eligibility, information supplied during the request, and the terms shown before acceptance. The app can make the application path feel quick, but approval and delivery are separate outcomes. Anyone opening it in a genuine emergency should leave enough time for those steps rather than waiting until the last possible minute.
My practical advice is to prepare before starting. Know the amount you actually need, check when your next reliable income arrives, and decide the maximum repayment you can handle without using another advance. This simple preparation makes the process faster because you are not making financial decisions while stressed. It also helps prevent the common mistake of borrowing a little extra just because the option appears available.
A realistic everyday scenario
Imagine a phone bill and a necessary grocery trip arriving in the same week that your salary is still several days away. A small advance could be useful if the amount is limited, the repayment date fits your income cycle, and the complete cost is clear before you agree. In that situation, I see the app as a possible bridge rather than a long-term financial solution.
The same scenario changes completely if your income is already committed to rent, utilities, transport, and existing debt. In that case, borrowing may only move the shortage forward. I would first look at a payment extension, a no-cost overdraft option, or help from someone I trust. The convenience of a mobile request should not make an expensive choice feel harmless.
Where the usual alternatives may be better
Compared with asking a bank for a conventional personal loan, a payday-style advance can feel more targeted and less formal. That may suit someone facing a small, temporary gap, while a bank or credit union is usually more appropriate for a larger planned expense or a repayment period lasting months. A bank account’s overdraft facility may also be preferable when its fees and limits are clearly understood.
Employer-based earned-wage access can be another better fit when it is available without a high cost, because it may connect borrowing to wages already earned. For a recurring shortage, none of these quick options solves the underlying problem. A spending review, a payment plan, or professional debt advice is more useful than repeatedly opening a cash-advance app.
The details I would inspect before accepting
The most important screen is not the first request button. It is the point where the full repayment obligation becomes visible. I would check the amount received, the total amount repaid, the timing of repayment, and every fee or charge shown in the agreement. If those details are difficult to understand, I would stop rather than rely on a general impression of speed.
I would also confirm that the repayment date matches the day money actually arrives, not merely the day it is expected. A weekend, bank delay, or payroll change can turn a manageable advance into an avoidable problem. Saving a copy of the agreement and noting the repayment date in a calendar are small steps, but they are especially valuable when the app is being used during a stressful moment.
Stability during repeated checks and everyday use
Repeated checks are a practical part of handling a financial request: I may need to revisit its status, compare dates, or make sure I have not mistaken an interruption for a completed submission. I would keep each check purposeful and avoid sending the same request again until I understand the visible result. With that everyday discipline in place, it becomes easier to judge whether the app remains a useful tool beyond the initial moment of urgency.
What happens when the app is used heavily
Finance apps are not usually “heavy” in the same way as games or video editors. The demanding moments here are more likely to be repeated form checks, switching between the app and banking information, reviewing terms, and returning later to confirm the status of a request. That kind of use rewards a clear, stable interface more than flashy visuals.
I would avoid repeatedly submitting the same request simply because the screen seems slow to change. Duplicate attempts can create confusion about which request is active and may make it harder to track what has actually been accepted. A better workflow is to wait for a clear result, take note of any reference or confirmation shown, and contact the relevant support route if the status remains unclear.
Another useful habit is to review the request on a reliable connection rather than while moving between weak signals. A dropped connection during a financial form is more serious than a paused entertainment app. If the screen reloads, I would first check whether the request was saved or submitted before entering the same information again.
Stability matters more than visual polish
My standard for this app is simple: financial information should remain understandable after returning to the app, changing networks, or taking a short break. I care less about animation and more about whether amounts, dates, and next steps remain easy to identify. The app’s job is to reduce uncertainty, not add another layer of it.
That is also why I would keep the application updated. The current version is 1.26, so users should make sure their installation is not unnecessarily behind before relying on it for a time-sensitive request. An update can improve compatibility or fix a problem, but it is still wise to avoid updating at the exact minute a bill is due. Checking the app earlier gives you time to recover if anything behaves unexpectedly.
Recovering from interruptions
If the app closes, the connection fails, or the phone runs out of battery halfway through a request, I would not assume success or failure from the interruption alone. I would reopen the app, review the visible status, and check any confirmation messages associated with the request. Only after that would I consider trying again.
This recovery approach is more important than it sounds. With ordinary apps, repeating an action is usually harmless. With borrowing, duplicate submissions or misunderstood statuses can affect your decisions and your records. I recommend keeping screenshots only for your own reference, while avoiding the storage of sensitive financial details in ordinary notes or cloud documents that are not properly protected.
Keeping personal information under control
Because this is a finance app, I would pay close attention to every field before submitting it. Enter only accurate information, review the destination details carefully, and avoid using a shared phone profile if other people can access notifications or app history. A strong device passcode and current system security are sensible companions to any borrowing service.
I would also read each permission or information request in context rather than approving everything automatically. The fact that an app is free does not make privacy irrelevant. The financial consequence of the advance is the central issue, but the handling of personal information deserves the same calm attention.
Device limits and compatibility
The app supports Android devices running version 6.0 or later, which covers a broad range of phones. That is helpful for people who keep an older handset, but compatibility alone does not guarantee a smooth experience on every device. Older hardware, limited free storage, aggressive battery-saving settings, or an outdated system browser can all affect how forms and account screens behave.
If I were using an older phone, I would close unrelated apps, keep enough storage free for normal updates, and disable battery restrictions only if the system was clearly interrupting the app. I would not install a separate “cleaner” or unofficial helper just to make a finance app work. Those tools can create more privacy and security questions than they solve.
A small screen can also make financial terms harder to inspect. I would rotate the phone only if the app handles it properly, enlarge system text when needed, and read the total repayment rather than relying on a cropped or abbreviated line. If the display makes an important figure difficult to understand, a larger trusted device or a desktop review may be safer than rushing on a phone.
Who will get the most value from it
I think the app is best suited to an adult who has a temporary, clearly measured cash gap and a realistic repayment plan. It may be useful for someone who values a mobile-first request and wants to consider an advance without starting with a branch visit. The free installation also makes it easy to inspect the process before deciding whether the terms make sense.
It is not a good choice for someone who needs a large amount, has irregular income with no dependable next payment, or is already using advances to cover earlier advances. It is also unsuitable for anyone who cannot understand the repayment obligation before agreeing. In those situations, a credit counselor, creditor payment arrangement, community support service, or lower-cost borrowing option deserves priority.
My performance verdict
From a performance perspective, the app’s appeal is its focused workflow rather than demanding technology. It is not the kind of application I would judge by graphics, background activity, or entertainment value. The meaningful questions are whether it lets me examine an offer without confusion, whether the request status is understandable, and whether I can recover safely after an interruption.
I like the idea of having a dedicated place to explore a small cash advance, and the strong user rating indicates that the experience has worked well for many people. At the same time, ratings cannot tell me whether a particular advance is affordable for my situation. The app can streamline access; it cannot remove the cost or responsibility of borrowing.
My final view is cautiously positive. Cash Advance Now - PayDaySay is worth considering as a short-term option, not as a routine way to manage monthly expenses. I would use it only after calculating the complete repayment, confirming the timing against my income, and comparing it with cheaper alternatives. If those checks pass, its focused design may save time. If they do not, the smartest performance improvement is to close the app and choose a solution that does not turn today’s shortage into next month’s emergency.
PayDaySay has kept the product accessible as a free finance app for Everyone, and its release on December 28, 2022, gives it an established place rather than making it feel like a brand-new experiment. Even so, my recommendation remains conditional: treat Cash Advance Now - PayDaySay as a carefully reviewed financial tool, read every repayment detail, and keep the borrowing amount as small as the real need allows.
FAQs for Cash Advance Now - PayDaySay
01What is Cash Advance Now - PayDaySay?
Cash Advance Now - PayDaySay is a financial service app designed to help users explore short-term cash advance and personal loan options. After entering basic information, the app may connect you with potential lenders or providers. It is important to understand that PayDaySay may not be the lender itself, and approval, loan amounts, fees, interest rates, and repayment terms depend on the provider that accepts your request.
02How does the application process work?
The process generally begins with an online form requesting personal, employment, banking, and income details. PayDaySay uses this information to evaluate or match your request with participating lenders. If an offer is available, you should review the agreement carefully before accepting it. Read every disclosure, including the annual percentage rate, finance charges, due dates, renewal conditions, and any consequences of late repayment.
03Are there eligibility requirements to use PayDaySay?
Eligibility requirements can vary depending on the lender and your location. Applicants are commonly expected to be adults with a valid identification document, a regular source of income, an active bank account, and a valid phone number or email address. Meeting these basic conditions does not guarantee approval. Lenders may also consider credit history, income, existing obligations, and state-specific lending regulations.
04How much does a cash advance or loan cost?
The cost depends entirely on the lender and the specific offer you receive. A short-term advance may include interest, an origination fee, a service charge, or other costs, and the effective annual percentage rate can be considerably higher than traditional credit. Before accepting anything, compare the total repayment amount with the money received and confirm whether automatic withdrawals or extension fees apply.
05Is Cash Advance Now - PayDaySay safe to use?
As with any financial application, use PayDaySay carefully and review its privacy policy, permissions, and lender disclosures before submitting sensitive information. Download it only from an official app store or verified source, and avoid paying an upfront fee in exchange for guaranteed approval. Never share banking passwords or verification codes. If you receive an offer, confirm the lender’s identity and licensing where required.
Pros
- Simple application process with minimal paperwork required.
- May help cover urgent expenses before your regular payday.
- Clear repayment terms can make borrowing costs easier to review.
- Useful for users with limited or no traditional credit history.
- Online access lets you apply without visiting a physical branch.
Cons
- Approval is not guaranteed and depends on lender requirements.
- Interest and fees may make the total repayment considerably higher.
- Short repayment periods can put pressure on your next paycheck.
- Availability and loan terms may vary by state or location.
- Late payments could lead to extra charges or affect your credit profile.

Cash Advance Now - PayDaySay
Gallery